CSRD software – how to find the right reporting tool
Is the Corporate Sustainability Reporting Directive presenting you with new challenges? The reporting obligation starts now…
he European sustainability directive CSRD (Corporate Sustainability Reporting Directive) is already omnipresent for many companies.
In the coming year, numerous companies will publish their first reports in line with the requirements of the ESRS (European Sustainability Reporting Standards).
Four German ministers have now approached the EU Commission in a letter with options to simplify sustainability reporting.
With Matchilla’s free and non-binding matching service, you can quickly and easily find the right ESG consultancy or software provider that fits your criteria.
The EU Commission already initiated infringement proceedings against Germany at the end of September because Germany, like 17 other European countries, was not able to transpose the directive into national law (the official deadline for this is 31/12/2024).
The European Sustainability Reporting Standards (ESRS), which specify the CSRD’s reporting obligations, are set out in Commission Delegated Regulation (EU) 2023/2772. As this is directly applicable EU law, no separate national transposition is required.
In Germany, starting with financial year 2024, almost 15,000 companies will be gradually required to provide sustainability reporting in accordance with the requirements of the CSRD and ESRS.
A large share of German companies has already addressed ESG. Numerous medium-sized companies are planning implementation with ESG consultancies and ESG software solutions or are already in the midst of their first dry runs for the reporting.
But now the EU directive is becoming a target in the German election campaign.
On 17/12/2024, a letter from ministers Wissing, Kukies, Habeck and Heil was leaked and circulated.
In this letter, the four ministers call on the EU Commission to align the CSRD reporting deadlines set by the EU for each company size with the deadlines of the planned CSDDD (European Supply Chain Directive).
The impact is summed up very well by the LinkedIn post by Maximilian Müller, Professor of Financial Accounting at the Faculty of Management, Economics and Social Sciences at the University of Cologne.
Clearly, the Green Deal is becoming an election campaign issue!
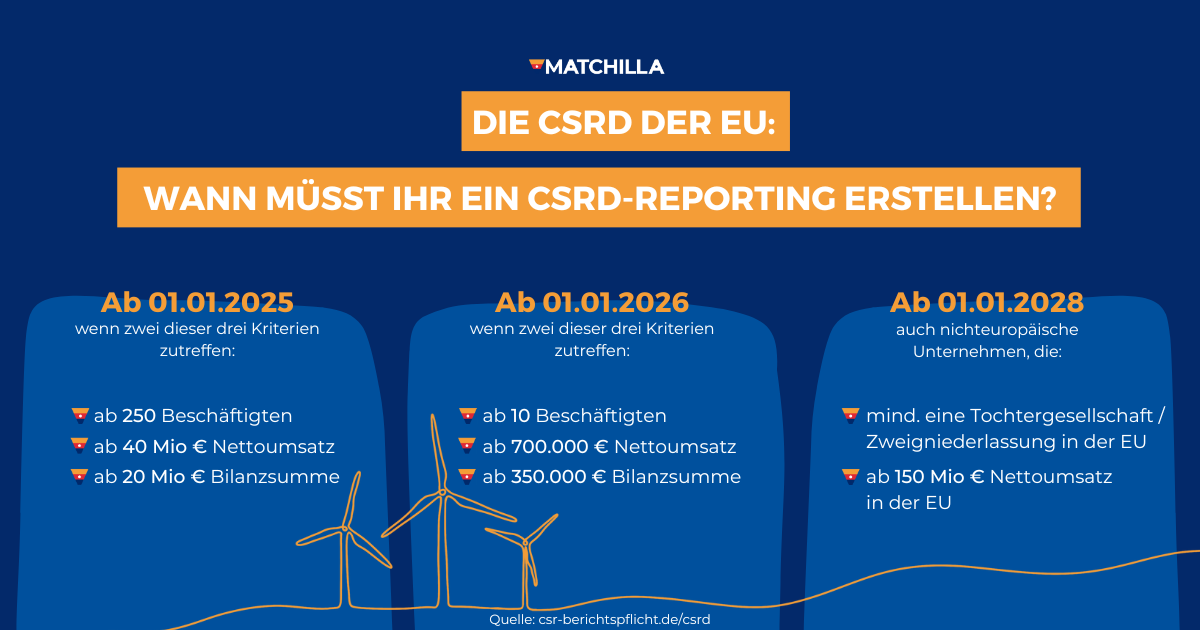
The EU provides for the following regulation as to when which companies are required to report:
The four German ministers are now demanding in their letter (in addition to various simplifications affecting reporting) a postponement of the reporting obligation as follows:
Postponement of the scope of application for large (non-PIE) companies from financial year 2025 to financial year 2027, with reporting in 2028. A corresponding postponement of also two years applies to PIE SMEs from financial year 2026 to financial year 2028, with reporting in 2029 (while maintaining the opt-out option for a further two years).
The ministers also propose aligning the size threshold for “large” companies in connection with sustainability reporting with the existing thresholds of the CSDDD (Corporate Sustainability Due Diligence Directive), i.e. the European supply chain law. This means that companies are considered “large” with net revenue of 450 million euros and 1,000 employees.
Every management team now has to weigh up how to position itself in response to this letter and take the utmost account of all legal aspects associated with this initiative.
In principle, as a reporting-obligated company you have two options for action:
Either you watch from the outside how the EU Commission responds to the ministers’ letter and what impact this response will have on Germany, hoping to avoid the impending resource effort many times over. However, this can become dangerous from a compliance perspective. And
if the German initiative fails, bottlenecks would arise across all areas of the ESG market.
Or you assume that the CSRD will come as planned at EU level, stay on it, and continue to do your CSRD/ESG homework.
You can think what you like about sustainability reporting. Making such a demand at this (late) point in time does not help any of the companies involved in any way.
We are currently continuing our research on this topic and regularly update the content here.
René Kühn is the founder and managing director at Matchilla. With experience from more than 500 ESG matchings for mid-sized companies and corporations, he and his team have been able to build one of the best market overviews of service providers for the various regulations.
Is the Corporate Sustainability Reporting Directive presenting you with new challenges? The reporting obligation starts now…
Are you looking for LCA software to manage your life cycle assessment data? We explain all…
Supply Chain Due Diligence Act: a somewhat cumbersome term (26 letters!) with meaningful benefits and new…